Exports Jumped 27.4%. Here's What That Does to Your Property Decision
A strong quarter is a real signal about the economy. It is a much weaker signal about whether this is your year to move.
The short read
Singapore's non-oil domestic exports rose 27.4 per cent year on year in the second quarter, driven by AI-linked demand for electronics and semiconductors. That is a genuinely strong print, and the transmission to housing is real but slow: hiring, then relocation, then rental demand, then — sometimes — prices. The lag is measured in quarters, not weeks.
The strength is also concentrated. Electronics is not the whole economy, and the districts that feel it first are the ones near where those jobs sit. A single quarter is not a trend, cooling measures have not moved, and interest rates still decide what you can borrow. If a piece of macro news changes your decision, the decision was not resting on much.
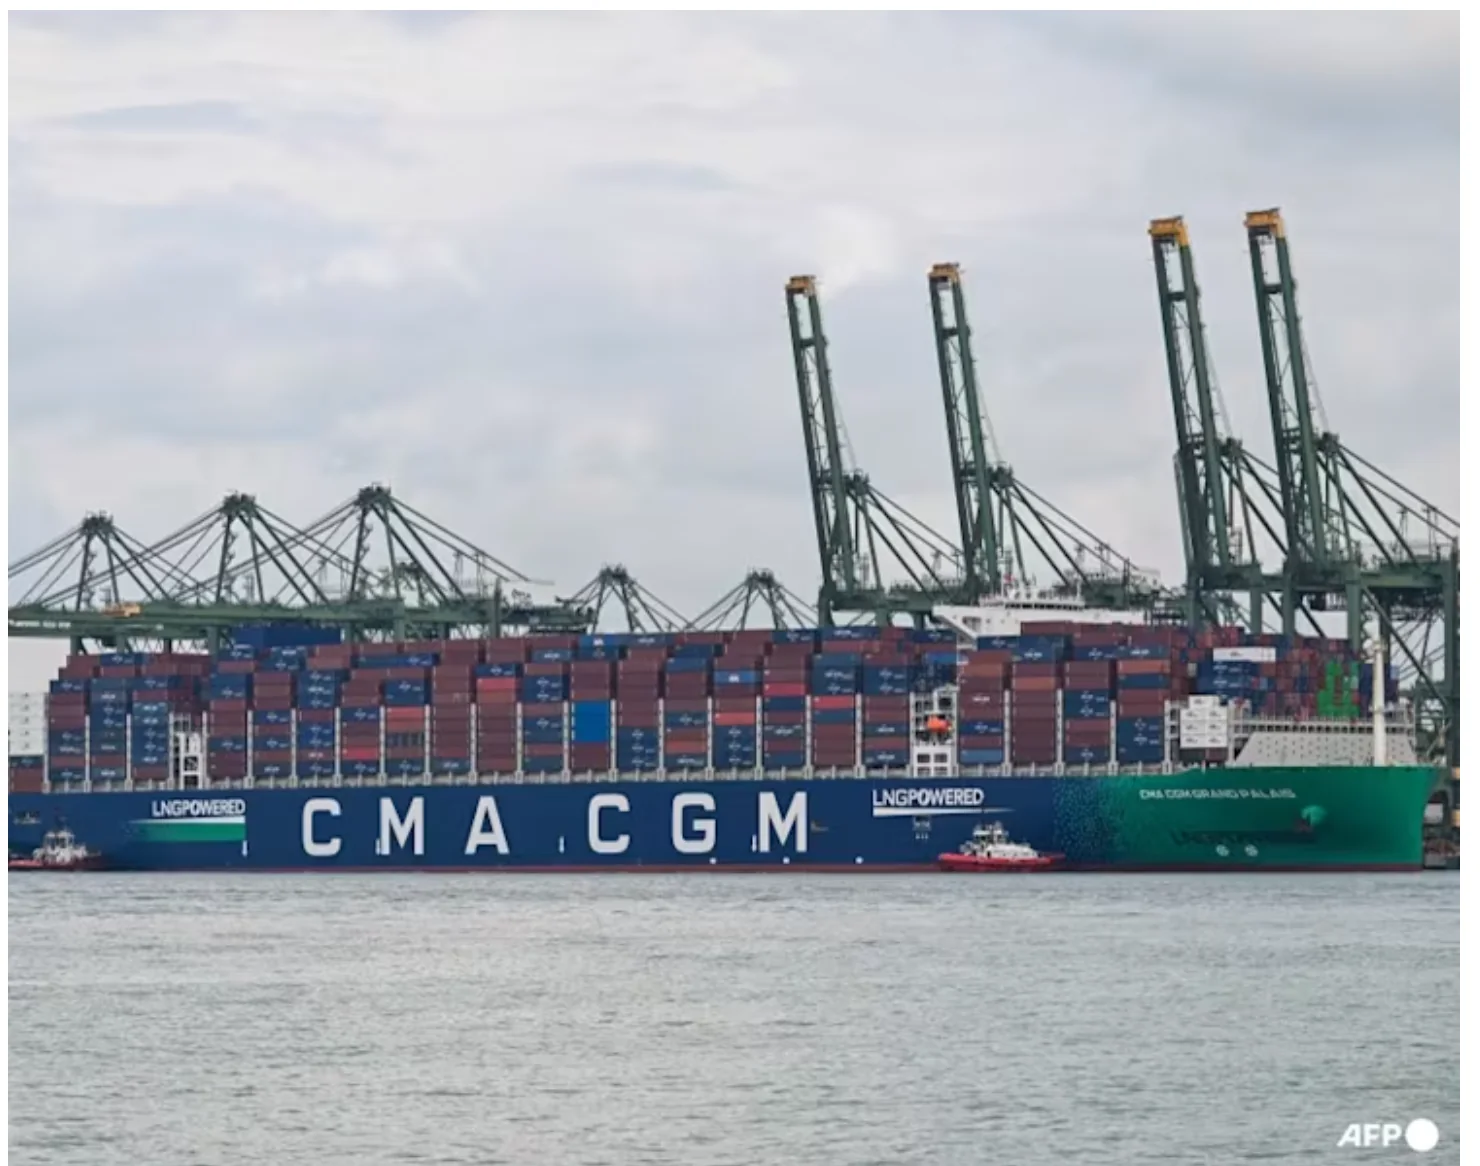
A client forwarded me the export numbers within an hour of them landing, with one line attached: does this change anything for us?
It is the right instinct and, usually, the wrong conclusion. So let me take the question seriously.
As CNA reported this week, Singapore’s non-oil domestic exports rose 27.4 per cent year on year in the second quarter, powered by AI-linked demand for electronics and semiconductors. That is a large number. It is not a rounding error or a base effect you can wave away — the world wants what a meaningful slice of this economy makes, and it wants a great deal of it.
The question is what that does to the roof over your head, and how quickly.
The chain is real, and it is slow
Here is the honest transmission, link by link.
Strong export demand supports corporate revenue. Revenue supports hiring and capital investment. Hiring brings people — some relocated from abroad, some moving between local firms with better packages. Those people need housing, which firms up rental demand first, because renting is what you do in your first year somewhere. Sustained rental strength eventually supports prices, because investors price yield and because some of those renters become buyers.
Every one of those links is real. Every one of them also takes time, and each can break. Hiring can be met with existing headcount. Relocation can be slower than expected. Renters can stay renters. In my experience the gap between a strong export print and anything visible in residential transaction data is measured in quarters — commonly two to four — and by the time it shows up, the next quarter’s news has already moved the conversation somewhere else.
This is why I am wary of any advice that puts before in the sentence. Buy before the market reprices. Move before the window closes. That framing turns a slow, uncertain chain into an urgent one, and the urgency is doing work that the data does not support.
Concentration matters more than the headline
The second thing worth saying plainly: this is not a broad-based boom. The strength sits in electronics and semiconductors, riding AI demand. Other sectors did not receive the same lift, and the households attached to them did not get the same year.
That has a direct consequence for property, and it is one the headline number hides. A concentrated boom produces concentrated housing demand. If a wave of hiring comes through the semiconductor and research layer, the pressure appears where those people work and along the lines that get them there — the one-north corridor, the Jurong Innovation District, the CBD fringe, and the rental stock within a reasonable commute of them.
It does not appear evenly. A landed enclave whose buyers are domestic, mostly upgrading from within a few kilometres and holding for a decade, is barely touched by a hiring cycle in electronics. Neither is a mature HDB town whose resale market is driven by families moving for schools and ageing parents.
So the useful question is not did exports rise. It is does this cycle put more people who want my kind of home within reach of my address — and for most families reading this, the answer is no, or not much.
One quarter is one quarter
I want to be careful not to talk anyone out of a genuinely good signal. If Q3 comes in similarly strong, the picture changes: two consecutive quarters is the beginning of a trend, and a trend is something you can plan around.
But a single print, however large, is a data point. Export figures are volatile by nature — they swing on shipment timing, on one large customer’s order book, on comparisons against a weak quarter the year before. Anyone treating one number as an inflection has skipped the step where you wait to see whether it holds.
Meanwhile, the things that actually govern your purchasing power have not moved at all. ABSD is what it was. TDSR is what it was. Loan-to-value limits are what they were. Your mortgage rate is set by conditions that have nothing to do with how many chips left Singapore in June. A strong economy does not loosen those, and if anything, sustained strength is the environment in which policymakers ask whether current settings are still doing their job.
What I would actually do with this news
Three things, none of them urgent.
If you are already selling or buying this year, note it and carry on. A firmer economy is a mildly better backdrop to transact into. Mildly. It does not justify re-pricing your expectations upward or accepting a weaker offer because things feel buoyant.
If you own an investment property near the affected employment nodes, watch your renewal. This is where a hiring cycle shows up first and most concretely. If your tenancy comes up for renewal in the next few quarters and your unit sits within reach of one-north, Jurong or the CBD fringe, the rental market may be a little firmer than it was. That is a real, checkable effect on your actual asset — which is more than most macro news offers.
If you were on the fence, stay on it, and re-examine your own numbers instead. The export figure tells you nothing about whether your family has outgrown its flat, whether your parents will need to live closer, or whether your cash position survives a two-month completion gap. Those are the variables that decide whether a move works.
The test I keep coming back to
When a client asks whether a piece of news changes their plan, I ask the same thing in return: if this had not happened, what would you be doing?
If the answer is the same thing, then the news is scenery. Interesting scenery — I read it too — but not instruction. And if the answer is something different, the honest follow-up is to ask what else would have to be true, and whether one quarter of one sector’s data is really enough to carry that weight.
Seventeen years in, the families I have watched do best were not the ones who read the cycle correctly. They were the ones whose move matched their own timeline, so they were never forced to sell into a bad month or buy into a hot one. The economy is the weather. Your timeline is the roof.
If you want to know what this cycle does to your particular position — a tenancy coming up, a decision you have been deferring — that is a conversation worth having on your actual numbers rather than a national one.
The numbers
| Headline | Non-oil domestic exports +27.4% year on year, Q2 2026 |
| Driver | AI-linked demand for electronics and semiconductors |
| Typical transmission lag | Hiring and relocation lead rental demand by roughly 2–4 quarters |
| Concentration | Growth led by one sector, not broad-based across the economy |
| Unchanged | ABSD, TDSR and loan-to-value limits |
| Source | CNA, 12 August 2026 |
Questions families ask
Will Singapore property prices rise because exports are up?
Not mechanically, and not on this alone. The honest chain runs like this: strong exports support corporate profits, which support hiring, which brings people who need somewhere to live, which firms up rental demand, which eventually supports prices in the segments those people rent and buy in. Every link in that chain can break, and the whole thing takes quarters to play out. Treat one quarter's export figure as directional support, not as a forecast.
Should I buy now before prices reflect the export boom?
That framing assumes the boom will show up in prices, that it will show up in your segment, and that it will do so before you would otherwise have moved. Three assumptions stacked on one quarter of data. If your family's timeline says move this year, move — but for your reasons. Buying early to front-run a macro trend is a trade, and most families are not in a position to hold a trade that goes against them for three years.
Which parts of Singapore benefit most from AI and electronics growth?
Follow where the work physically happens. Electronics and semiconductor employment concentrates around the west and north-east industrial belts, while the research and corporate layer clusters at one-north, the Jurong Innovation District and the CBD fringe. Rental demand from a hiring cycle shows up near the jobs and near the MRT lines that reach them — not evenly across the island, and not in landed enclaves whose buyers are domestic and long-tenured.
Does a strong economy override the cooling measures?
No. ABSD, TDSR and loan-to-value limits are policy settings, not market outcomes, and they do not relax because a quarter came in strong. In fact the relationship often runs the other way: sustained strength is exactly the condition under which policymakers consider whether current settings are tight enough. Plan on the rules you have.
How much should macro news influence when I move?
Less than almost anyone selling you something will suggest. In seventeen years the families who did well were not the ones who read the cycle correctly — they were the ones whose move matched their own timeline, so they were never forced to transact at a bad moment. Macro tells you the weather. It does not tell you whether the house you are standing in still fits.
Reporting referenced: CNA. Analysis and views are Adrian Lim's own.
Talking it through beats reading about it.
If this story touches a decision your family is weighing, send Adrian a message. A first conversation costs nothing and commits you to nothing.
WhatsApp Adrian · +65 8183 2333More from Insights
What OpenAI's S$300 Million Actually Means for Your Home
A capability story and a price story move at very different speeds — and confusing the two is how families overpay for headlines.
The Greater Southern Waterfront: Reading a 30km Story on Family Time
A 30-kilometre transformation is not one decision. It is several, on different clocks — and the clock that matters most is your family's.
Marina One's $1,702 psf Record Low: What It Tells You About CCR Value
A record low at Marina Bay made headlines this week. The number is the easiest part of the story — the harder part is what it means, and for whom.